


Separate FLSA premium
If a statement separately reports the FLSA overtime premium, use that amount as the starting estimate.
Use your pay records to estimate the FLSA overtime premium. The result is before deduction caps, income phase-outs, and other personal tax limits.
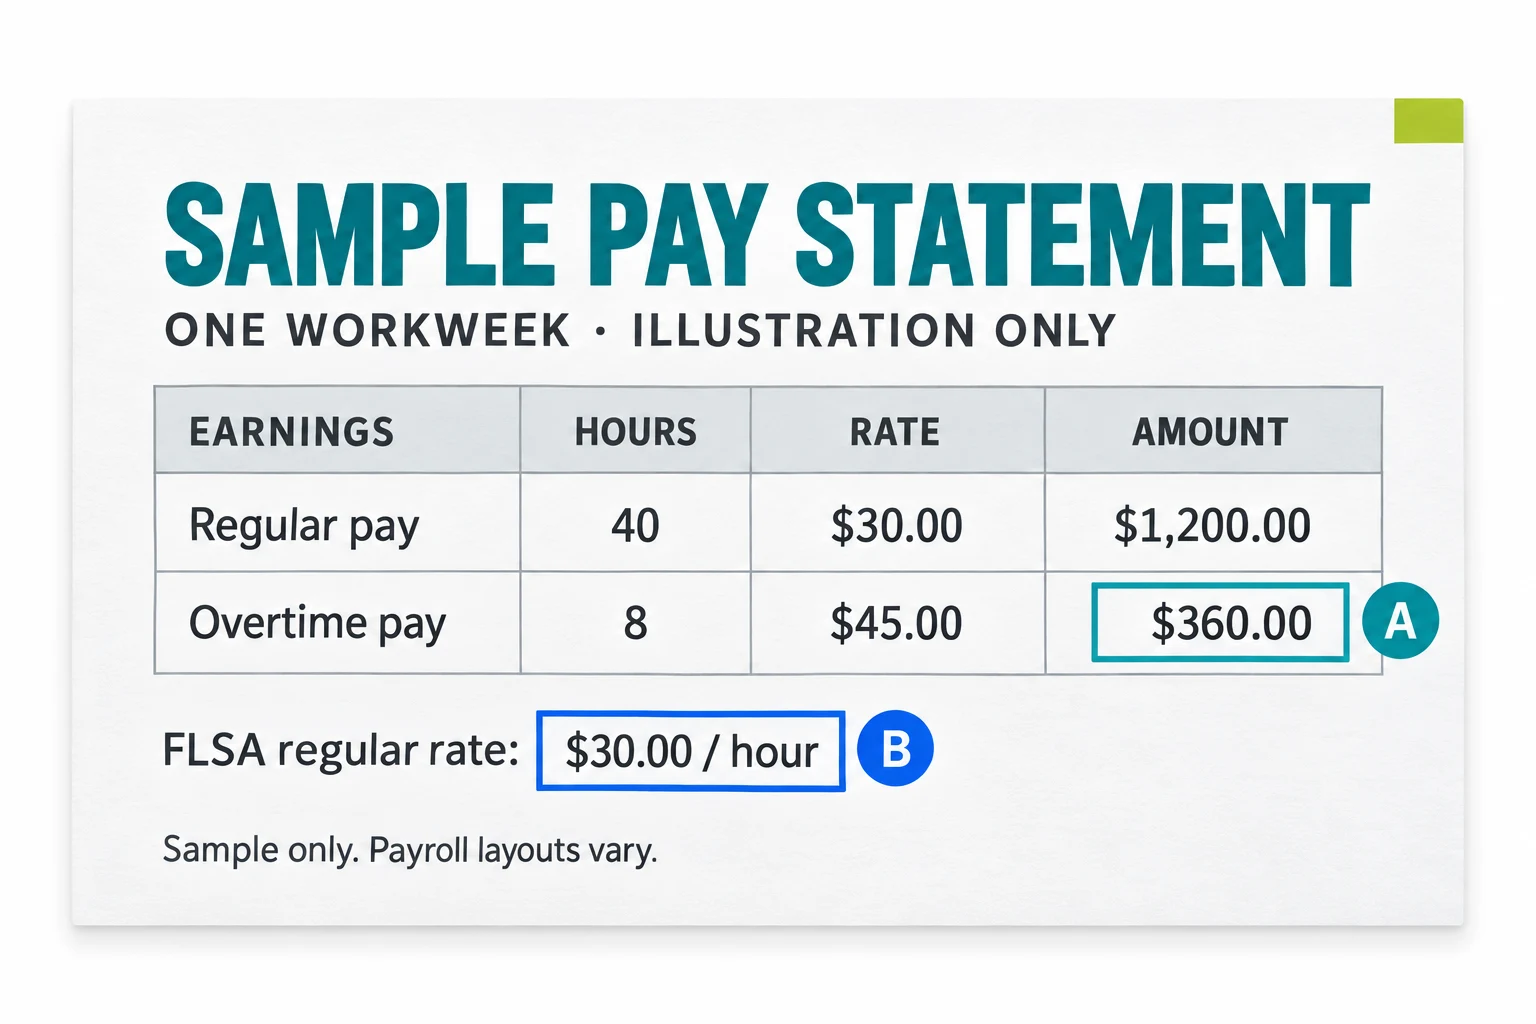
A STANDARD TIME-AND-A-HALF EXAMPLE
At a $30 regular rate, 8 overtime hours pay $360. Of that, $240 is the regular-rate portion and $120 is the half-time premium.
$30.00 × 0.5 × 8 hours = $120.00
Assumes FLSA-covered, nonexempt overtime in one workweek. Personal limits and reporting rules still apply.
Use a separately reported qualified amount if you have one. Otherwise, choose total overtime pay or enter your regular rate and hours. Keep the statement you used so payroll or your tax preparer can check the result.
If a statement separately reports the FLSA overtime premium, use that amount as the starting estimate.
For standard time-and-a-half pay, the premium is one third of total overtime earnings. The rest is the regular pay for those hours.
If overtime was paid above time-and-a-half, the estimate should isolate only the FLSA-required half-time premium portion.
If no annual statement is available, estimate from regular rate and overtime hours, then keep notes showing why that method was used.
The result estimates your qualified overtime compensation. Your deduction may be lower because of annual caps, income limits, or other tax rules.
For an annual total, you can also review the filing-status cap and check whether your MAGI may trigger a phase-out warning.
Official sources
Source baseline checked 2026-09-08
Defines qualified overtime compensation, FLSA overtime eligibility, deduction limits, reporting rules, and taxpayer requirements.
View official sourceSummarizes the deduction cap, MAGI phase-out thresholds, Social Security number rule, and 2025 reporting note.
View official sourceProvides 2025 methods for individuals estimating qualified overtime compensation when separate reporting is not available.
View official sourceExplains 2026 Form W-2 reporting, including Box 12 code TT for qualified overtime compensation.
View official sourceExplains the FLSA overtime baseline for covered, nonexempt employees working over 40 hours in a workweek.
View official source